"“We have lent a huge amount of money to the U.S. Of course we are concerned about the safety of our assets. To be honest, I am definitely a little worried.” "


Chinese premier Wen Jiabao 12th March 2009


""We have a financial system that is run by private shareholders, managed by private institutions, and we'd like to do our best to preserve that system."


Timothy Geithner US Secretary of the Treasury, previously President of the Federal Reserve Bank of New York.1/3/2009

Showing posts sorted by relevance for query coal imports. Sort by date Show all posts

Tuesday, October 11, 2005

Drax - sunset on the UK energy industry

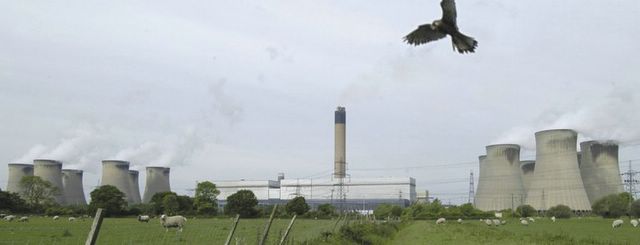
Drax Power Limited owns and operates Drax Power Station, the largest, cleanest and most efficient coal-fired power station in the UK.

The generating units are fitted with flue gas desulphurisation (FGD) equipment removing 90% of SO2 from emissions, and work is underway to reduce still further emissions of oxides of nitrogen (NOX).

The plant is experimenting with bio fuels (willow chips) and petcoke which is a recovery from oil refining.

By-products of the coal combustion and FGD processes are recycled through their further use in the construction industry.The plant output 4,000 megawatts, 7% of the UK's electricity needs.

Drax Group Limited
…is Incorporated in the Cayman Islands Co No WK-129356

Registered Office
Walkers SPV Limited
Walker House
PO Box 908GT
Mary Street
George Town
Grand Cayman
Cayman Islands
British West Indies


Today the company announced someone wanted to buy them…and the plant which is a core component of the UK energy supply. …

Drax Group Limited ("Drax") today announces that it received on 10 October 2005 a new approach from a consortium regarding a possible cash offer for Drax. The proposal is subject to a number of conditions, including due diligence and financing, and is an alternative to the listing. Drax is seeking further clarification on the initial approach...

It was only a few weeks ago that someone else wanted to buy them ..

The Board of Drax Group Limited ("Drax" or "the Company") announces that it received on 12 September an indicative approach from a consortium comprising Constellation Energy Group, Inc and Perry Capital LLC regarding a possible cash offer for Drax representing an enterprise value of £1.9 billion. The proposal is subject to a number of conditions, including due diligence and financing...


But the Directors turned the offer down.

So how is it that a shadowy group of investors, located in the Cayman Islands have become a much wanted asset ?

Briefly, In 1990, the electricity industry of England and Wales was privatised under the Electricity Act 1989. Three generating companies and 12 regional electricity companies were created. As a result of privatisation, Drax Power Station came under the ownership of National Power, one of the newly formed generating companies.

Due to changes in the structure of the market , needs for cash, a change in strategy in 1999 Drax Power Station was acquired by the US-based AES Corporation (A Delaware based outfit) for £1.87 billion. Of course it wasn’t their money, they borrowed it and so they ended up with a raft of creditors, which when things went sour they couldn’t pay.

So they “restructured” the debt , which meant the “D” level guys were toasted but the “A” level creditors , some of whom like mining giant BHP Billiton were supplying the plant with coal.

Following a series of standstill agreements with its creditors, the AES Corporation and Drax parted company in August 2003. Just months later in December 2003, creditors overwhelmingly supported a financial restructuring scheme that put Drax into the ownership of a number of financial institutions.
On December 22, 2003, The Debevoise & Plimpton partnership (fancy US corporate lawyers) could announce, after drawing monster fees, that Drax Power, Europe’s largest coal-fired power station, had successfully restructured its ₤1.3 billion senior secured debt. Debevoise & Plimpton LLP represented Drax Power in this transaction.(Once owned by the British Public)

The successful restructuring puts Drax, which supplies 8-10% of Britain’s power, in a strong financial position going forward. The refinancing involved concurrent schemes of arrangement in England, Jersey and the Cayman Islands, and a Section 304 bankruptcy court proceeding in the United States.

The BBC reported that there were four bids considered for re-structuring which took the form of complex offers to buy out portions of the plant's debt.

BHP Billiton's offer, worth an estimated £95m, would see holders of Drax's A-2 debt get 70p in the pound. International Power another energy company offered 65p in the pound for A-2 debt and 55p in the pound for B debt. Goldman Sachs the bankers were offering 64p in the pound for A-2 debt and 50p in the pound for B debt.


Money market men said that the deal was finally agreed at what represented approximately 70p per pound of debt. In brief they bought £1.34 Bn of assets at a discount of 30% = £ 938 Mn (give or take a few bob).

Since taking over ownership effectively from Jan 1st 2004, the company has seen the price of wholesale electricity climb from £24 per Megawatt Hour to £48 MWH, which is the good news, the bad news is the price of coal has gone from under £10 a ton to £25 a ton. However the owners have seen for example Nett profits for the first 6 months of 2005 at £227 Mn and interest has been paid at the rate of £160Mn per year (mainly to the owners) who bought that debt. (Caveat - the £227Mn profit includes one off payments from TXU Europe whose bankruptcy caused AES to founder – but this was factored into the buying price because it was problematic at the time and required an Act of Parliament to change the rules so they could get the money).

So not exactly a wild cash cow, but has been a nice little earner that Debevoise & Plimpton partnership and (Morgan Stanley hovering in the background) put together…and now someone else wants to have a share of the action.

So that’s OK for the UK ?

Well up to a point Lord Copper.

Drax has contracts for coal with UK Coal, (the rump of the NCB after Maggie destroyed it) who are the biggest UK (in fact only) coal miner. Figures for the year ended December 2004 showed pre-tax losses deepened to £51.6 million, from a loss of £1.2m in 2003. Deep-mine output dropped from 14.8 MN tonnes in 2003 to to 12.0 million while surface mine output was down from 3.1 Mn tonnes to 2 MN.

When posting half-year losses of £30.6m, UK Coal warned attempts to support further development at Rossington had failed and that the mine would be mothballed – the same fate as Harworth mine once current extraction is completed.

Their shares up from a low of the mid 40’s pence in early 2003 have moved sideways at 140/145 p for nearly 12 months, bn 3200Mn of that is surface property and landholdings, the last asset of the old NCB.

Now Tom Farmer famous for his Kwit Fit chain is said to want to buy the property portfolio and there is talk of an offer of 180p – 200p per share. Farmer is working with Alchemy Partners who lost out on MG and also the bachelor Lord Buccleuch, the only landownder in Scotland whose estates are so large you cannot ride across them on a dhorse in a day.

The shares haven’t moved, principally because nobody wants to run mines that lose £36Mn in 6 months.

Which is why the figures for coal imports into the UK make such interesting reading. In 2004, Coal imports increased by 20 % - a new record level. 72% of the United Kingdom’s imports of coal came from just three countries: South Africa, Australia and Russia. A further one fifth of coal imports came from three additional countries, Colombia (steam coal), USA (mainly coking coal) and Indonesia (steam coal).
Steam coal imports came mainly from South Africa (34 %), Russia (33%) and Colombia (12 %). Imports of steam coal from the USA were substantially higher in 2004 than 2003, accounting for 2.4 per cent of the total in 2004 compared with less than 0.1 per cent of the total in 2003. Imports of steam coal from South Africa in 2004 were more than double the volume imported in 2000. All but a very small fraction of UK coking coal imports came from Australia (65 %), the USA (21 %) and Canada (11 %).


So this is where our with the wonderful far sighted New Labour White Paper Energy policy.

An irreplaceable national source of electricity, owned by a bunch of financiers operating out of a nameplate in the Cayman Islands.

A company being stalked by the funny money men.who have no interest in UK energy independence.

This company relies upon a company mining coal which is evident cannot carry on mining / trading, (even if Tom Farmer rides in and picks up their property assets)
....... Unless of course the Government see that they can add some more subsidies to the pot – and there have been plenty in the last few years, disguised in a variety of ways.

Suddenly nuclear power stations look like a good idea.(if not the only)

Recent blogs on same topic here

Monday, October 10, 2005

Essential UK energy information

I have just discovered the excellent site “Vital Trivia” by Chris Vernon who provides a succinct overview of the UK energy supply system, derived from the new DTI Energy Trends report and comes to these conclusions. Essential reading.

· Total energy production 7½ % lower than Q2 / 2004.

· Oil production fell by 10 % compared to Q2/2004 as production from older established fields continued to decline.

· Gas production fell by 5½ per cent compared Q2 / 2004. Gas imports increased by 53½ % while gas exports declined by 26½ per cent. The UK was a net exporter of gas in the Q2 / 2004, albeit 74½ per cent lower than in 2004. UK gas demand was 2 per cent higher than a year earlier.

· Coal production declined by 20 % year on year (UK Coal lost £50Bn plus). Coal imports increased by 20 % - a new record level. Generators’ demand for coal was up 6½ per cent. (As the financiers sweat dirty old crumbling ancient power stations).

· Allowing for calendar differences, year on year , coal supplied ½ % more electricity, gas supplied 4½ % less. Nuclear supplied ½ % more. Net imports of electricity were 20 % higher than a year earlier.

He concludes

“Although this report does show supplies to be adequate it makes in my opinion some extremely optimistic assumptions about gas and electricity imports, relying on untested infrastructure and untested magnitudes and similarly optimistic assumptions on CCGT electricity generation substitution.”
Basically it's a back of an envelope calculation to see how the UK energy industry is falling headlong into energy importation and loss of energy security and with a tiny excess capacity - gone are the heady post war days when the fleets of coal fired stations were operating at 50-60% capacity.

He raises three main concerns in the outlook for the Winter of 2005 as a result of reading the Ofgem forecasts ;

· In Winter 2004, 331 million cubic metres per day gas was used in UK. Forecasts for “beached” gas have been lowered from 226 to 327 mcm/d and even this may be optimistic. There were record supply disruptions last year.

· The refurbished Isle of Grain LNG terminal, will import 13 mcm/d rising to 17 mcm/d (maximum capacity of the terminal) during the very coldest days. The terminal isn’t even operational yet and early shipments have been diverted to the the US. The US is also facing shortages and importers are dominating supplies from Africa and Middle East.

· The Intercontinental interconnector has a very finite capacity -It is assumed that 42 mcm/d will be available. In 2004 the capacity of the Interconnector was 25 mcm/d but despite acute gas shortage and extremely high prices in the UK the market responded by reducing imports.

To which can be added;

· Assuming continental weather is the same as UK, harsh conditions will not encourage EU suppliers to ship gas needed at home.

... and of course we need to pay for those imports. No more an energy island, we face the problems Japan faced many years ago.

Tuesday, January 01, 2008

Year end thoughts on energy, food and the Presidential hopeful and hopeless

Low oil prices at the start of the year eased fears of an energy crisis. With the dollar rallying, WTI would eventually sink below $50 per barrel. But world oil production wasn't growing and the performance of some producing regions were showing concerning signs. Mexico was clearly suffering from Cantarell's decline, the Caucasus kept raising question marks (a situation later updated here) and there are also major comcerns over Saudi Arabian production figures.... Don;t expect any reduction in the forthcoming 12 months.


Weary soothsayers will turn again to Mr Hunts Site, Signs of the Economic Apocalypse for a yearly roundup....

"The most striking change of the past year in the markets is the sharp rise in gold (32%) and oil prices (57.5%) and the 11.5% drop in the value of the dollar against the euro. The past year also saw the end of economic optimism in the media as the housing bubble finally burst."

He quotes David Seaton on the FT journo ( and Bilderburg visitor) Martin Wolf

"If we examine what Martin Wolf is saying logically, not even really reading between the lines, this supremely informed man is declaring that he knows that, before they ever pay Scandinavian like income taxes, drive small cars and wear sweaters around the house on cold winter days, the elites of the United States will create a police state and go to war endlessly to dominate the resource rich areas of the world."


It is frightening that these people write (it appears) endlessly about the threat from ex Arkansas Governor Huckabee who is several shed loads short of a full load. He has no chance of the nomination and is unelectable... for more reasons than it is worth enumerating.

As worrying, and something Mr Hunt never touches on is the future cost of food - this, driven by world demand from the emerging economies, droughts, crop failures and the politically inspired drive and publically subsidised rush into fuels from crops will lead, with higher housing costs (rents / mortgages / land) to higher inflation (already concealed by the Fed failing to re cord M3 and plainly juggling the COL indices.

Nothing so far deflects the serried ranks of advisers to Lord Patel from the firm belief that Fred Thompson will be the next President of the United States.

Perhaps looming on the horizon is a worse fear expressed early in the year over world coal supplies for energy by Shaun Chamberlin at the Oil Drum .

The general consensus view on coal supplies has long been that we have hundreds of years of the stuff left, and that oil and gas depletion are the pressing concerns. However, dissenting voices are emerging. Canadian geologist David Hughes recently claimed that "peak coal looks like it's occurred in the Lower 48 (US states)", and the consensus position on coal is also called into serious question by the Coal: Resources and Future Production report soon to be released by the Energy Watch Group in Germany.

For example did you know ...the US has now switched from being a net exporter to a net importer of steam coal and arguing that total (volumetric) US coal production will peak between 2020 and 2030.

Only 15% of coal produced globally is exported, the rest being consumed domestically, Australia is responsible for almost 40% of global coal exports. The UK relies for 65% of it's coal on imports. Read on >>>>>


...which is why there are never less than 50 coalers lined up outside the port Newcsatle in Australia at any time and when there is a storm that disrupts supplies it has global ramifications on supplies, stocks, availability and prices. see previous post

Saturday, June 09, 2007 Chinese Coal carriers grounded off Newcastle,NSW, Australia

More revent

Newcastle Coal Trades Near a Record as Demand Rises (Update1)
Dec. 31 (Bloomberg) -- Coal prices at Australia's Newcastle port, a benchmark for Japan, South Korea and Taiwan, traded near a record on concern that demand is outpacing supply.

Power station coal, excluding shipping cost, for delivery within three months posted its second weekly gain, settling at $89.69 a metric ton in the week ended Dec. 28, according to the globalCOAL NEWC Index, an Asian benchmark calculated each Friday. Prices are up 85 cents from the previous week and near the US$89.76 record set earlier this month (nbspNEWC Index up from US$67.72 in September).

``It's going to be a situation of restricted supply throughout 2008, so that will keep spot prices near record levels,'' said Gavin Wendt, a senior resources analyst at Fat Prophets Funds Management in Sydney. ``The miners just can't get the stuff out and onto a ship.''

The queue of ships waiting outside Newcastle port to load coal reached a record 79 in June after storms disrupted operations. There were 34 vessels waiting to load as of midnight, Dec. 30.

Chinese coal imports rose 39 % to 46.68 million tons in the first 11 months of 2007.

Final Cheering message..

The Paris-based International Energy Agency (IEA ) projcts global energy needs growing 55% between 2005 and 2030, ( annual rate of 1.8%,) with almost half of it in China and India. Despite political;;y based efforts to boost the use of biofuels worldwide, the IEA says fossil fuels will remain the dominant source of primary energy, accounting for 84% of the overall increase in demand between 2005 and 2030. (*See Hillarys crazy energy plans)

Electricity use will nearly double, with most new plants burning coal. (In the UK E.ON is to build the first new UK coal-fired power station since 1974, at Kingsnorth in Kent. RWE Npower wants to follow suit with two more, in Essex and Northumberland; Scottish and Southern Energy will submit plans for a plant near Pontefract. ) Aging and less-productive oil fields and resistance among major oil exporters to build spare oil capacity will make crude oil and natural gas more expensive and prompt developing countries to turn increasingly to coal as fuel.

The IEA also says global oil demand will hit 116 million barrels a day by 2030, up from about 85 million barrels a day now.

Happy New Year

Saturday, August 18, 2007

UK rail freight grows and buys trains, special high capacity, hi-tech trucks from overseas


EWS Construction is the dedicated rail operator for the construction and waste markets and is part of English Welsh & Scottish Railway Ltd which has now been re-nation alised - this time by Deutsche Bahn the German state owned Railways.

They have just ordered 34 new aggregate hopper wagons adding 600,000 tonnes of additional haulage capacity per annum - In the last five years the aggregate rail market has grown by one billion freight tonne kilometres.

This requirement is to help meet the demands of contracts recently placed with SWS by CEMEX UK (The 100 year old US cement manufacturer who took over Ready Mixed Concrete/Rugby Cement in 2005)

The wagons have been built in Poland by the huge US group Greenbrier's European plant at WagonySwidnica S.A., in Swidnica Poland. They will be fitted with "track friendly suspension systems" supplied by Axiom Rail ( a subsidiary of EWS formed from their takeover of Probotec Ltd of S. Wales in 2005) , for delivery in spring 2008.

GB Railfreight was formed in 1999 and is part of FirstGroup plc, their current (and fast growing) buk frieght includes the movement of desulphogypsum (DSG) for British Gypsum from West Burton power station in Nottinghamshire to Kirkby Thore in Cumbria, and natural Gypsum from East Leake, Leicestershire and Robertsbridge in East Sussex.

(Desulphogypsum (DSG) is a by-product of Flue Gas Desulphurisation (FGD) plants, installed at some coal fired power stations in order to reduce sulphur emissions, and is now used to substitute natural gypsum. Although DSG cannot replace the high quality mineral in terms of range of end-uses, it has proved suitable for plasterboard manufacture accounting for about half of total demand.)

GBFr will be operating at 100% capacity for coal hauling by mid 2008 and so have ordered 72 new high capacity (74.5 tonnes) coal hopper wagons and used for hauling (by the new Class 66 trains made in Canada by General Motors) from Welbeck and Thoresby collieries to West Burton and Cottam Power Stations.

GBRf also won 2 coal contracts for handling imported coal in less than a year.

1. Drax Power Limited, for the movement of imported coal from the Port of Tyne to Drax power station near Selby North Yorkshire started April 2007.
2. EDF Energy (French National Energy Company) for movement of coal from the Port of Hull to Cottam and West Burton power stations in Nottinghamshire to started July 2007.

The order has been placed with IRS (Roumanian rail company based in Luxembourg) and be built by the recently acquired Astra Vagoane company in Arad, Roumania which started making trains in 1891 (and where the first electric train system in eastern Europe was developed in 1913) and deliveries commenced in February 2007 These trucks with low track force bogeys can operate anywhere in the UK.

UK coal production in Q1 2007 fell 28% to 4..0 Mn. tonnes (opencast by 42%) coal imports were 12.2 Mn tonnes of which 84%, was steam coal for the power station market.

So the UK mines less coal, imports more (75% of demand) to be used in power stations increasingly foreign owned (often nationalised utilities) to be hauled by Canadian trains, using Polish and Romanian waggons by the German State Railways (excepting the new GBRf company).

This is what the UK Gubment presumably calls their energy security policy.
Photograph of a GB Railfreight GBRf Class 66 66712 at Pelaw with 6H90 Port of Tyne - Drax power station imported coal train.Photo Ian Britton.

Monday, September 25, 2006

The EU's dependence on imported energy grows

Statistics on energy for the EU25 have been published by Eurostat today.

Briefly the EU in 2005 consumed 1, 637 million tonnes of oil equivalent ( TOE see footnote) much the same as 2004.

EU25 production of all sources of energy fell by 4.2% in 2005, and net imports rose by 4.5%. Consequently the EU25 depends on imports for 56% of its energy needs, up from 54% in 2004.

If a longer time frame is considered between 1995 and 2004 energy consumption in the EU25 rose by 11%, production fell by 2%, and net imports rose by 29%.

Energy consumption per capita in the EU25 in 2005 was equivalent to 3.6 TOE in 2005, US = 7.8 TOE/capita and Japan 4.1 TOE/capita.


All EU25 indigenous energy sources types fell in 2005,

1. Crude oil declined 9.0% over 2004
2, Natural gas by 5.8%
3. Coal by 5.7%
4. Nuclear energy by 1.3%.

The UK accounted for 70% of the crude oil produced in the EU25 (a decline of 11% on previous year), followed by Denmark 15% of production which declined by 4%.

The UK was also the EU25's largest gas producer = 44% of production declining by 7.7% over 2004, the next was Holland with 32% of production which declined by 6%.

Poland, was EU25's largest coal producer with 57% of the coal mined and production declined by 2.1%. In Germany (19% of the EU25 total) and the United Kingdom (13%), the 2nd and 3rd largest coal producers, production decreased by 3.9% and 17.9% respectively.

France, which produced 46% of all EU25 electricity from nuclear sources and production increased by 0.9%, the 2nd largest supplier, Germany (16% of market) production (through plant closures) fell by 3.0%.

Oil imports (60% of energy imports) rose 3% in 2005 and gas (25%) 9.2%. (see pic of LNG tanker - soon to be seen in Milford Haven ?)

Member States dependence on imports varies from Cyprus, totally dependent, Portugal 99.4% to Denmark, which produces more energy than it needs, is a net exporter of energy. The UK is currently 13% dependent and is planned to be 80% dependent by 2020.

A tonne of oil equivalent (toe) is a standard unit defined as ....

A TOE, Tonne of oil equivalent , is One tonne of oil with a net calorific value of 41.868 Gigajoules. A convenient although not wholy accurate common measure so one Giga Joule of nuclear power = 0.024 tonnes of oil, and one tonne of high grade coal = the same amount of energy as 0.7 tonnes of oil.

For more on energy security concerns go here

Friday, February 08, 2008

Floods wreak havoc in Queensland coalfields - global coal prices shift up a gear


The flooded Ensham mine in Queensland.

The coal industry is worth more than Aus$18 billion a year to Queensland's economy and employs about 23,000 people in the state. Floods in January have caused major and massive problems - Coal giant Xstrata lost production at its Collinsville and Newlands mines, BHP Billiton has been forced to cut back production at different sites. Rio Tinto said production at its Kestrel mine had been hit.

Ensham Resources Pty Limited, is one of Queensland's largest and fastest growing thermal coal producers, they built the world's second largest dragline at their Emerald mine in the coal-rich Bowen Basin in central Queensland. It is a major source of coking coal for the steel industry.

Industry sources say that prices at the end of 2007 of US$ 95-US$100 pe tonne can be expected to rise to US$150 a tonne, as supplies are hit not only by flloding of mines but disruption to rail services to the coast.

On top of this, it is apparent that China's severe winter will impact on demand and consequently on already record global prices.

The bucket attached to the new Ensham dragline is of 143 cubic yard capacity - it can scoop out enough material to fill two backyard swimming pools in one go.

Now the dragline is in it's own swimming pool.

"It's really a scene of utter devastation", says Peter Westerhuis general manager of the mine, "the Ensham mine has got the Nogoa river running almost through the middle of it. It's burst it's banks and engulfed the entire centre of operations. The pits are up to a hundred metres deep, and the ones that have been completely inundated are about three kilometres long each, and full of water. We estimate a hundred thousand megalitres has gone into those pits.

"We had some indication of rising flood levels in the Theresa creek, which feeds into the Nogoa river. Literally, twenty four hours later we were faced with this devastation.

The Queensland Resources Council says it could be weeks before the mining industry returns to normal production after the widespread flooding through the central highlands at a cost to the industrysaid to be over Aus$200 Mn.

"The mine is constructed with levees in appropriate places. They are classified as levees suitable for a one in a hundred year flood, in excess of anything that's happened here before. But the flood levels have gone completely over the top of the levee, it's really an unprecedented, and unexpected event that no one could predict." (Just compare the size of this mutha with the pic at the top)

Might be an idea to send details of this to the boffins at the bank of England ... perhaps if they had read about the storms in Newcastle in June they might have been ready to forecast the rise in world coal / energy prices. Saturday, June 09, 2007 Chinese Coal carriers grounded off newcastle,NSW, Australia

and ...

Newcastle Coal Trades Near a Record as Demand Rises (Update1)

Dec. 31 2007 (Bloomberg) -- Coal prices at Australia's Newcastle port, a benchmark for Japan, South Korea and Taiwan, traded near a record on concern that demand is outpacing supply.
Power station coal, excluding shipping cost, for delivery within three months posted its second weekly gain, settling at $89.69 a metric ton in the week ended Dec. 28, according to the globalCOAL NEWC Index, an Asian benchmark calculated each Friday. Prices are up 85 cents from the previous week and near the US$89.76 record set earlier this month (nbspNEWC Index up from US$67.72 in September).

``It's going to be a situation of restricted supply throughout 2008, so that will keep spot prices near record levels,'' said Gavin Wendt, a senior resources analyst at Fat Prophets Funds Management in Sydney. ``The miners just can't get the stuff out and onto a ship.''

The queue of ships waiting outside Newcastle port to load coal reached a record 79 in June after storms disrupted operations. There were 34 vessels waiting to load as of midnight, Dec. 30.

Chinese coal imports rose 39 % to 46.68 million tons in the first 11 months of 2007.

Must be very difficult to calculate global energy price trends faced with that sort of information. Evidently judged by the performance of the wankers at the Bank of England.

UPDATE Midnight : The FT has just hit the streets ....

Wheat price surge raises inflation fears By Chris Flood in London
A fall in US inventories of wheat to a 60-year low drove prices of the grain sharply higher on Friday to a fresh record, intensifying fears of rising global food price inflation.

US wheat futures jumped by their daily trading limit every day this week. Prices for benchmark flour making Minneapolis , (MGEX) rose 10.7 % on the week, extending its price surge since the beginning of 2008 to 50%.

To cope with the raised prices MGEX Contracts Committee approved raising wheat contract daily price limits from 30 cents to 40 cents effective with the Feb. 12 trading session.

Thursday, January 04, 2007

UK Quarterly Energy Production / Usage / Prices- Production & Usage down and Prices up

Energy Trends and Q3 2006 Quarterly Energy Figures and Prices were published by the DTI today - fascinating - but extraction of meaningful information is tedious , here are the edited highlights.

Energy Trends has articles on:
"World production, consumption, reserves and trade in natural gas"

World gas reserves are estimated to be about 180 trillion cubic metres or 62 years of production at 2005 rates. Russia has 27 %, Iran 15 %, and Qatar 14 %t (Where US CENTCOM is located) . 23% of gas is transported as LNG = 100% in Japan.

"Electricity transmission across Europe in 2004".

Detailed information from the International Energy Agency's "Electricity Information" volume which shows that within the EEA only 1% of electricity is imported,but flows between countries can be very large and significant - and result in major disruptions as has been seen in the last two years . Emphasising the synergy between countries such as France, Germany, Luxembourg, Switzerland, and the Slovak Republic are very important to the integrity of the European grid.

The UK imports less than 3 per cent of its electricity consumption and exports only 1/2 per cent of its production - solely with France.

As a Very Important adjunct to reading this, Europe’s principal grid authority the "Union for the Co-ordination of Transmission of Electricity" (UCTE) published a detailed interim report into the grid disturbance that left 15 million households without power, and came close to resulting in a pan-European blackout in the autumn. UTE reported that " the causes of the event were multi-factorial, but that the key trigger was an unexpected rise in the load on the Landesbergen-Wehrendorf grid link, which joins the grid control areas of E.ON Netz and RWE. The precise causes of this increase are at present not clear, or have not yet been published, but the role of an unpredicted rise in wind generation (documented by E.ON Netz) appears to be a potentially important feature." Further more UCTE makes it clear that the subsequent behaviour of uncontrollable wind generation was a significant factor in the development of the crisis and the difficulties that the grid operators experienced in restoring the service. UCTE notes (p. 25) that 60% of wind units tripped in response to the emerging crisis, and then began automatically reconnecting (p. 26ff) exacerbating an already grave situation (p. 30). The E.on / Netz report into the event is available here

All of which might indicate , that at last, someone should be wakening up to the threats to UK Energy Security and place less reliance on wind power ..... See FOOTNOTE

As well as these articles, there are tedious self congratulatory details of changes in reporting to meet the DTI's commitment (which have holes in due to the sell off of the National Grid) in the February 2003 Energy White Paper to produce more information at regional and local level - for what it's worth.

The UK Quarterly Energy statistics for the 3rd Quarter of 2006 throws up some startling comparisons with the same Quarter in 2005 (to which all comparisons relate) ;

1 Indigenous production of primary fuels was 42.4 Mn. tonnes of oil equivalent (TOE) a reduction of 7.8%

2. Energy consumption was 1.9 % lower

3. Consumption on a primary fuel input basis (on a Seasonally adjusted
and temperature corrected - annual rate ) 220.0 was 220.0 Mn TOE up a marginal 0.4%.

4.Other solid fuel (coal, petcoke,biofuels) consumption rose by 21.2 %.

5 Oil consumption decreased by 1.8 per cent.

6 Gas consumption fell by 5.2 per cent.

7 Primary electricity consumption decreased by 7.1 per cent.

Noticeably the generators are shovelling coal as long as possible whilst they can and keeping gas production in mothballs - lower input costs using well depreciated plant and minimal maintenance. It also suggests that the impact of higher consumer and industry prices is having an effect on consumption. Which is not suprising as squirelled away are the figures for Domestic fuel prices ...

Overall the price paid for all fuel and light by household consumers has risen by 25.1 % in real terms between Q3 2005 and Q3 2006, the highest rate in the last 30 years.

Domestic electricity prices, including VAT, in Q3 2006, were 22.4 per cent higher in real terms than in Q3 2005. The price of domestic gas rose by 34.2 per cent in real terms over the same period, with the price of heating oils rising by 5.4 per cent.

Estimates from the International Energy Agency suggest that in October 2006, UK domestic electricity and gas prices, including taxes, remained below the EU15 median although average annual gas bills rose 19.8% (approx £87 per household) and electricity 15.7 % ( £55 per household) year on year. ( i.e wholesale prices at the Year end still have to work through into Quarterly bills). Many UK Domestic consumers have operated on capped and fixed length tariffs many of which end in Jan 2007. See BBC Story here So many consumers can expect a very sharp increase in prices in the first 2007 Quarterly bill.

Broken down into their constituent parts the figures produced show ;

COAL: QUARTER 3 2006

1. Provisional figures for Q3 2006 show coal production down 24.1 % at 3.6 Mn Tonnes (deep mined production 23.4% down and opencast 25.6% down..

2. Whilst coal imports grew 18.8 % at 13.0 million tonnes, a new quarterly record.

3 Coal consumption for Q3 2006 was up 18.5% @ 13.5 million tonnes ( electricity generators consumption up 23% in period)

4. Coal stock rose 3 MN tonnes to 18.5 Mn tonnes (say 4 months usage)

Remember the heady days when we used to dig this stuff out of the ground ? Mrs Thatcher's Reganomics put an end to that old son.

OIL: (Crude + NGL's) QUARTER 3 2006

1 Total indigenous UK oil production down by 10.2 % to 17.3 million tonnes. 2 new fields started up in September - insufficient to make up for production declines in older fields.

2. Again the UK was a net importer of oil and oil products in Q3 2006 by 2.5 Mn tonnes. (Q3 2005 = 2.3 Mn tonnes)

3 Overall primary demand for oil products in Q3 2006 was down 2.6 %.(19.9 Mn tonnes)

4. Motor spirit (petrol) fell 2.4 % = 4.63 Mn tonnes)
Derv rose by 5.8 % = 5.2 Mn tonnes (God knows what it was in Northern Ireland where dodging duty is a 3rd religion)
Aviation turbine fuel was down by 1.8 % = 3.52 Mn tonnes

Road fuel Prices show that in mid December a litre of unleaded petrol was on average 87.4 pence per litre unchanged from a year earlier and Derv was 93.0 pence per litre, 1.2 pence per litre higher than a year earlier. which gave "green" Gordon a chance to add a penny or so on the duty with impunity.

GAS: (Terawatt hours TWh) QUARTER 3 2006

1 UK indigenous production of natural gas in Q3 2006 was down 2.4 %

2. UK was a net importer Q3 2005 (9.3 Twh) and moved into being a net exporter again in Q3 2006 ( 1.9 Twh) exports and imports of natural gas increased by 62.8 % and 14.2 %.

3 Demand for gas in Q3 2006 was down 10.3 %.

4 Gas use (Provisional figures) for electricity generation was down 11.7 % and domestic use 11.4%

ELECTRICITY (TWh) : QUARTER 3 2006

1 Electricity generators fuel consumption was down by 1.1% and electricity supplied (77.4 TWh) .was 0.5% lower than Q3 2005 (Domestic (23.76 TWh) down 0.5% / Industrial (23.76 TWh) 0.2% down / others - street lights, telecomms etc., (23.36 TWh) down 0.4% )

2. Coal usage was up 22.9 %
Gas use was down 11.6 %
Nuclear production was down 8.1 % ( maintenance and outages)
"Renewable Hydro" was down 6.1%

3. For those curious to know wind , energy has an installed capacity of 630 MW which mean (if 30% efficient - which is optimistic) = 210 MW see British Windy Energy Association site
experience is starting to show that production from wind farms is never at the level forecast before the projects begin.

Also see Renewable Energy Foundation reports on wind farms 9/12/06 - report on actual data via ROC's claimed. (actual efficiency UK wide = 28.4%) Quote "the new research offers predictions which are in keeping with Danish and German empirical experience and demonstrate the need for a broader spread of investment in the renewable sector"

Remember ! Indirect subsidy approaching £1 billion a year is being channelled towards renewable energy by the Government’s Renewables Obligation - wind farms, farm ROC's, not wind.

ENERGY PRICES: QUARTER 3 2006

1. In Q3 Average industrial gas prices, were 20.0 % higher in real terms compared to Q3 2005 (incl CCL) coal was lower by 10.5% and heavy fuel oil up 10%.

2 In Q3 Average industrial electricity prices were 27.9 % higher in real terms, in Q3 2006 compared to Q3 2005.(incl CCL)

3 The International Energy Agency provisiona figures suggest that in 2005, average UK industrial gas prices were below the EU/G7 median, and industrial electricity prices were around the EU/G7 median.

4 DTI Estimates suggest that in October 2006, industrial gas and electricity prices in the UK including taxes were above the EU15 median for all consumers available from this source.

If you want more - Energy Trends and the Quarterly Energy Prices bulletins, are available in hard copy from DTI on subscription, price £40 per annum or are available for downloading at http://www.dti.gov.uk/energy/statistics/publications/index.html

Subscription form is also available @ http://www.dti.gov.uk/energy/statistics/publications/trends/index.html

More detailed annual data on energy production and consumption for the years 2000 to 2005 are available in the DIGEST OF UNITED KINGDOM ENERGY STATISTICS 2006, published by the Stationery Office on 27 July 2006, priced £39.50. or @ http://www.dti.gov.uk/energy/statistics/publications/dukes/page29812.html

FOOTNOTE

The well scrubbed and smartly dressed, but remarkably dumb, Mike O' Brien, one of the many short lived New Labour Energy Ministers 25.10.04, Hansard
To achieve that target, we need to make use of all renewable sources. We expect 7 or 8 per cent. of the 10 per cent. generation to come from wind energy. Other technologies will be hard pushed to produce the rest.

Saturday, January 12, 2008

Nuclear winter - less energy at higher cost

Chris Vernon at the Europe Oil Drum has an excellent and comprehensive review of the Government announcement about the nuclear plant program announced by John Hutton this week. He asks ."considering the nuclear cliff, (see Chris's chart below - note the assumptions are optimistic ...but Sizewell will probably last a bit longer) has the decision come too late to maintain the nuclear contribution?"

Even on the most optimistic assumptions the answer is .... yes.

"EDF Energy anticipated this decision and in September of 2007 submitted the plans for their 1.6GW EPR (Evolutionary Power Reactor) power station to the UK regulators for design assessment ( Press Release). Detailed information on this design is available from the EDF/AREVA website: http://www.epr-reactor.co.uk/. This is the same design as is being built in Finland at Olkiluoto and in France at Flamanville.

The Finland build is the first one and has had some problems. Initially it was meant to cost 3.7bn euro and be complete in 2009, construction started in 2004. Since then there has been a 2 year slip and the cost increased by 1.5bn euros. So we're looking at 7 year build time and 5.2bn euro (£3.9bn - say 14 times the commitment by BOE to Northern Wreck) . See also Lord Patel post Friday, August 17, 2007 British Energy Nuclear Fleet production down 17%, profits by 14%

Chris ends on a pessimistic note ..

UK gas production will be almost over by the end of the next decade leaving the country reliant on imports from Norway, Russia and beyond. This raises serious question marks over the long term viability of the 36% electricity the country currently generates from gas. In addition to that approximately one third of the existing coal fleet is scheduled to close under the EU Large Combustion Plant Directive.

In times of hardship EU directives will be the first thing to ignore but even the coal supply is questionable as the UK imports most of its coal and is now competing in an increasingly competitive market.

In 2006 the UK generated 394 TWh of electricity - Chris asks ...."what will the country generate in 2020? " Not to mention a looming skills gap in the UK nuclear industry.http://business.timesonline.co.uk/tol/business/industry_sectors/utilities/article2806400.ece
Essential reading for every one who votes.


PS The UK will be importing some 30% of UK gas consumption this winter.Source DBERR (UK govt Dept of Business Enterprise, formerly DTI)

Coal production in Britain has fallen to its lowest level since the industrial revolution, according to data from the Office for National Statistics. Annual production is set to fall below 15 million tonnes, a level last seen 200 years ago. See Chris's chart above for a historical perspective and the increasing reliance on imports by the UK energy industry.

Also Newcastle Coal Trades Near a Record as Demand Rises
Dec. 31 2007 (Bloomberg) -- Coal prices at Australia's Newcastle port, a benchmark for Japan, South Korea and Taiwan, traded near a record on concern that demand is outpacing supply. ...

PPS : January 31st 2005 in the early run up to the 2005 General Election, Tony Blair (then Prime Minister) discussed with Manchester Evening News readers the introductin of nuew nuclear power stations - for the first time ever in public during his presidency term of office.

"We don't have any plans to open new power stations but what you are saying isinteresting and I think there is a debate to be had about nuclear power but it has to happen in a rational way. If we suggest a new generation of nuclear powerin this country I can guarantee there will be public concern about it so wewould have to look at what is going on in other countries very carefully."

Well they have been carefully examining it for 3 wasted years - a trifle faster than the opvernight (well .... over a weekend) decision to fund Northern Wreck ( another rational decision ?) .... this was not picked up by the national / international Press / TV (who were present) at the time. The metropolitan muttering classes don't really concern themselves with what happens in Manchester.

Friday, March 30, 2007

Fiddling whilst the lights go out

The Department of Trade and Industrypublished the Energy Trends and Quarterly Energy Prices today :

TOTAL ENERGY: 2006

- Total production in 2006 was 196.4 million tonnes of oil equivalent, 8.8 % lower than 2005.
- Between 2005 and 2006 coal and other solid fuel consumption rose by 11.0 %
- Oil consumption increased by 1.1 %
- Gas consumption fell by 5.5 %.
- Primary electricity consumption decreased by 6.5 %.


COAL 2006

Annual coal production for 2006 was 18.6 Mn tonnes, 9.3 % down on production in 2005 at 18.6 million tonnes. Opencast production was down 17.3 per cent as sources declined in output.

- Imports of coal in 2006 were record level of 50.3 Mn tones , 14.3 per cent up on 2005
- Coal demand was 68.2 Mn tonnes up 10.2 %

OIL: 2006

- Compared with 2005, Total indigenous UK production of crude oil and NGLs in 2006 decreased by 76.6 mn tonnes = 9.6 %. Two new fields started production in 2006, but production from these new fields was insufficient to make up for the general decline in production from older established fields.

- The UK was a net importer of oil and oil products for the first time since 1980 by 6.6 million tonnes. In 2005 the UK was a net exporter by 2.4 million tonnes.

- Overall primary demand for oil products in 2006 was 0.4 per cent lower than in 2005.

- Deliveries of aviation turbine fuel increased by 0.1 %. Preliminary figures for 2006 suggest that motor spirit deliveries fell by 1.7 per cent whilst Derv (diesel) deliveries increased by 5.6%

GAS: 2006

- Total indigenous UK production of natural gas in 2006 declined by 8.6 % over 2005.
- Exports of natural gas in 2006 rose by 25.4 % compared with 2005 and imports increased by 40.8 %.
- Demand for gas in 2006 as a whole was 4.4 % down on 2005.

Gas use for electricity generation in 2006 was 7.5 % down on 2005.
- Provisionally, consumption in the domestic sector fell by 3.6 % in 2006 as a whole while consumption in the industrial sector fell 4.7 %.

ELECTRICITY: 2006

- Fuel used by generators in 2006 as a whole was, in total, 0.3 % lower than in 2005. (ie Static)
- The supply from coal in 2006 increased by 11.6 % (+14.9 TWh)
gas fired stations supply fell by 7.5 % (-11.2 TWh).
The supply from nuclear stations fell by 7.9 % (-5.9 TWh).
- Total electricity supplied by all generators in 2006 was 0.4 per cent lower (-1.7 TWh) than in 2005. (ie Static)

PRICES: QUARTER 4 2006

- Average industrial gas prices, including CCL were 14.9 % lower in real terms in Q4 2006 compared to Q4 2005.
- Average industrial electricity prices including CCL were 14.6 % higher, in real terms, in Q4 2006 compared to Q4 2005.
- Estimates suggest that in January 2007, industrial gas and electricity prices in the UK including taxes were above the EU15 median for all size bands of consumers.
- In mid March 2007, unleaded petrol was on average 88.5 pence per litre, a decrease of 1.0 pence per litre compared to a year earlier.
- In mid March 2007, diesel was, on average, 92.2 pence per litre, 1.6 pence per litre lower than a year earlier.
- Provisional Q4 2006 data shows that the price paid for all fuel and light by household consumers has risen by 26.4 % in real terms between Q4 2005 and Q4 2006.
- Domestic electricity prices, including VAT, in Q4 2006 were 24.3 % higher in real terms than in Q4 2005. The price of domestic gas rose by 37.6 % in real terms over the same period, whilst the price of heating oils fell by 6.9 %.

- 2006 figures for household bills suggest that an average standard credit electricity bill increased by £53 compared to 2005 bills. Bills for direct debit and pre-payment customers increased by £44 and £55 respectively.

- For gas, 2006 bills suggest that an average standard credit bill rose by £87 compared to average 2005 bills. Comparable changes for average direct debit and pre-payment bills were increases of £71 and £97 respectively.

- Combined gas and electricity standard credit bills have increased by about 18.0 per cent in real terms, and 20.9 per cent in cash terms, between 2005 and 2006.

- The Energy White Paper, published in February 2003, defined four goals for energy policy, the first of which was to put ourselves on a long term path to reduce the UK's CO2 emissions by 60 per cent by 2050; this target was emphasised in the 2006 Energy Review, and the draft Climate Change Bill published in March 2007 proposed that the 60 per cent target would be legally binding.

- Final energy consumption increased by 9.5 % between 1990 and 2006 compared with a GDP increase of 47 % over the same period.

- Energy consumption did not change at the same rate as GDP due (says the DTI) to:
1. Improvements in energy efficiency
2. Fuel switching
3. A decline in the relative importance of energy intensive industries
4. Demand for space heating does not increase in line with output.
...ie no mention of cost increases.

Energy Trends and the Quarterly Energy Prices bulletins, published quarterly, are available in hard copy from DTI on subscription, price £40 per annum and on the internet at

It is evident that UK electricity producers are sweating their coal burning assets whilst they can and that the consumers both commercial and domestic have been jolted into more efficient energy use by the dramatic rise in price.

Natural gas and oil assets continue - like coal (open cast production declined) to decline at a masive rate. This cold and lonely island on the Western fringe of Europe, hads to importing more and more energy either as gas by tanker or pipeline, oil or coal. Whilst people worry about the impact of carbon emissions on the economy over the next 40 years, the impact on the balance of payments, competitiveness of UK industry and the cost of living - especially of the ageing population ,is, it appears, of little concern.

Fiddling whilst the lights go out.

Thursday, July 17, 2008

Public Service Announcement for UK Treasury, BERR, Bank of England, Foreign and Commonwealth Office , FSA , MEPC etc., etc., URGENT

This is highly specialised secret information about the prospects for coal / iron / freight rates from Brazil / Australia which may have an impact on future industrial / energy costs for the whole of the UK.

The sources are very difficult to find and require very skilled operators to develop economic espionage networks (pic Lord Patel discussing price of conch shells used as currency by primitive Pacific islanders - newspapers, TV news, speaking to folks involved with iron ore / coal imports, heavy users of same etc., people in bus queues, ..... (BTW Aluminium - the principal component of which is electrical energy, has also hit all time highs ever, of US$ 3,100- US$ 3,200 per metric tonne for Primary Aluminium 3mo Official Confirmed)

Platts are reporting some remarkable figures on bulk cargo mineral freight rates some of which are at historical highs and are expected to go higher as winter approaches.

Capesize ships from Brazil to China and/or Southeast Asia iron ore is being fixed at the US $88.00-88.50/mt level for 160,000 mt cargoes (up from mid June US$82/mt) although they have dropped from May all time highs of US $108.50/mt but are still at historically high levels.

For example South Korea's Posco fixing a 170,000 mt iron ore cargo from Ponta da Madeira to Kwangyang on an August 1-15 loading window at $88.50/mt on a Transfield ship that has yet to be nominated.

These rates apply to SE Asian destinations other than the China mainland especially South Korea, as Chinese charterers have cut back spot buying and rely on longer term iron ore contracts for 2008/2009. Chronic port congestion at the main discharge terminals and a need reduce stockpiles to more manageable levels after the plant shutdowns to ensure clean air for the peking Olympics has slowed spot buying.

Western Australia to China freight rates have fallen dramatically by some 50% since mid-May, when the market peaked at around $48/mt - related essentially to the consequences of flooding in the fields. (see Friday, February 08, 2008 Floods wreak havoc in Queensland coalfields - global coal prices shift up a gear )

On Monday, BHP Billiton fixed a 170,000 mt cargo from Port Hedland to Qingdao at $27/mt for a late July-early August loading window on the 2006-built, Mineral Shikoku (206,312 dwt). The same charterer also reportedly fixed a 160,000 mt cargo from Port Hedland to Qingdao for a July 25-30 loading window at $28/mt on the 1995-built Bet Scouter (173,149 dwt). It is of interst to note here that BHP Billiton have closed a deal with South Korean steel giant Posco for a price of US$300 (A$325) a tonne for coking coal in 2008-09, up from US$97 in 2007-08.

"Coal prices rose throughout the year to record highs. The price of annual coal delivered to European ports, commencing January 2009, rose from US$72/tonne at the start of April 2007 to US$124/tonne as at 31 March 2008. (British Energy Half year results to 31/3/08 Page 12 )

Longer shippping times from Brazil are affecting prices as Iron ore , loading in Western Australia can be in China in two weeks, once the ship leaves its loading port .

Australian suppliers are expecting Iron ore prices to rise 70-85% this year and thermal coal for power stations is expected to more than double from its existing level of US$56 a tonne.

The impact of the coking and thermal coal price rises alone would boost Australia's annual 2008-09 export revenue by $35 billion to $56billion.

PS : If you don't work for UK Treasury, BERR, Bank of England, Foreign and Commonwealth Office , FSA , MEPC etc ., but know someone who does .. pass it on.

Tricky work being an economic spy .. salt water plays havoc with yer Gucci loafers.

Thursday, June 28, 2007

DTI publish UK Energy Trends Q1 2007

Department of Trade and Industry have published Energy Trends and Quarterly Energy Prices Trends today for the 1st Qtr of 2007

Here is a quick snapshot -

- Q1 2007 Total indigenous UK production of crude oil and NGLs decreased 4.5 % on Q1 2006.

- Q1 2007 Total indigenous UK production of natural gas
decreased by 16.8% on Q1 2006

- Q1 2007 Total indigenous UK production of coal
decreased by 27.9% on Q1 2006

Total electricity generation from all renewable sources in 2006 was 18,133 GWh, 7.5 % up on 2005... approximately 3 % of all electricity generated.

Here are details filleted from the complete reports available at the DTI website.

TOTAL ENERGY: QUARTER 1 2007

- Total production in the first quarter of 2007 at 49.3 million tonnes of oil equivalent was 13.3 % lower than in the Q1 2006.
- Total inland consumption on a primary fuel input basis was 240.3 million tonnes of oil equivalent in the Q1 2007, 1.8 % lower than in theQ1 2006.
- Between the first quarters of 2006 and 2007 coal and other solid fuel consumption fell by 13.4 per cent.
- Oil consumption increased by 2.5 %.
- Gas consumption rose by 6.3 %.
- Primary electricity consumption decreased by 27.8 %.

COAL: Q1 2007

- Provisional figures for Q1 2007 show coal production down (due entirely to mine closures) 4.0 Mn tonnes - down 27.9 %per cent on Q1 2006 at 4.0 . The decrease was the product of a fall of 42.0 % opencast production fell by by 13%
- Imports of coal in Q1 2007 were 2.3 % down on Q1 2006 12.2 million tonnes 10.2 Mn tonnes (84%) of which, was steam coal for the power stations market.

OIL: QUARTER 1 2007

- Total indigenous UK production of crude oil and NGLs in Q1 2007 decreased by 19.9 Mn tonnes a decrease of 4.5 % on Q1 2006. This included production from 3 new fields which started production during the year ending march 2007, including the very large Buzzard field.
- The UK was a net exporter of oil and oil products in the first quarter of 2007 by 0.1 million tonnes.
- Overall primary demand for oil products in the first quarter of 2007 was 5.1% lower than Q1 2006.
- Motor spirit deliveries rose by 0.1 %. Derv fuel deliveries increased by 3.8%. Deliveries of aviation turbine fuel rose by 9.3 %. reflecting the increase in air traffic movements, especially by low cost airlines.

GAS: QUARTER 1 2007

- Total indigenous UK production of natural gas in the first quarter of 2007 was 16.8 % down on Q1 2006.
- Compared with Q1 2006, exports of natural gas in Q1 2007 increased by 44.1 per cent and imports increased by 50.6 per cent.
- Demand for gas in Q1 2007 was 3.4 % lower than in Q1 of 2006.
- Gas use for electricity generation increased by 34.2 % and domestic consumption fell 12.9% public administration, commerce and agriculture consumption fell by 11.2 % and in industrial sectorby 12.3 %.

ELECTRICITY: QUARTER 1 2007

- Fuel used by generators in Q1 2007 was, in total, 8.8 % lower than Q1 2006.
- Coal use during the quarter was 21.1 % lower than a year earlier.
- Total electricity supplied by all generators in Q1 2007 was 4.8 % down (-5.1 TWh) than a year earlier.
- In Q1 2007 final consumption of electricity fell by 4.1 % Domestic use by 6.2 % and consumption by commercial, public administration, transport and agricultural customers was down by 1.3 % and Industrial use of electricity was 4.4 % lower.

ENERGY PRICES: QUARTER 1 2007

Average industrial gas prices fell 32% , Average industrial electricity prices rose 7.0 % in real terms.

- In mid June 2007, unleaded petrol was on average 96.6 pence per litre, an increase of 1.3 pence per litre compared to a year earlier.
- In mid June 2007, diesel was, on average, 97.2 pence per litre, 0.5 pence per litre lower than a year earlier.
The price paid for all fuel and light by household consumers has risen by 22.9 % in real terms between Q1 2006 and Q1 2007.
Domestic electricity prices, including VAT, in Q1 2007 were 21.1% higher in real terms than in Q1 2006.
Domestic gas prices rose by 33.7 % in real terms over the same period, whilst the price of heating oils fell by 12.1 per cent.
Estimates suggest that in April 2007, domestic gas prices in the UK, including taxes, for medium sized consumers were the second lowest in the EU15 and domestic electricity process were fifth lowest.

RENEWABLES: 2005

Electricity generated from all renewables as a percentage of total UK electricity generation rose to 4.6 per cent in 2006 using the international definition of renewables. In 2005 on the same basis it was it was 4.2 per cent.
In 2006 the percentage of UK electricity sales that were from sources eligible for the Renewables Obligation (RO) was 4.4 % up from 4.0 % in 2005.
Total electricity generation from all renewable sources in 2006 was 18,133 GWh, 7.5 per cent up on 2005.
Generation from biofuels grew by 3 %, within which landfill gas was the main contributor. There was no growth in the contribution from the co-firing of biomass with fossil fuels.
Generation from offshore wind grew by 49 per cent; and generation from onshore wind grew by 27 per cent.
As at 31 December 2006, 449 projects contracted under the Non Fossil Fuel Obligation (NFFO), the Scottish Renewables Orders (SRO) and the Northern IreIand NFFO had been commissioned and were generating electricity, with a capacity totalling 1,200 1,200 MW. Total renewables capacity in the UK at that date was 3,613 MW = 30% utilisation overall.

Monday, July 03, 2006

Tony Blair tells the TRUTH helps kick start a green revolution... and stirs a few memories

(Bateman cartoon coming on here). Yes. Tony Blair told the Truth....TRUTH.

It happened when he was entertaining the British Society of Magazine Editors at NO 10 Downing Street (See No 10 website) .... there he was explaining .."Now as I say people always talk about me as if I am sort of starry eyed about people who have made money, I am not,..."

Q:
(Top shelf wank mags for kids) Question:It is a question about top shelf magazines ... vocal threat emerging from parliament ..... I wondered whether you felt it necessary that they should be displayed on the top shelf or that they should have age stamps?

Tony Blair
: I don't know what I think about this actually. I don't really know, I don't know. The only thing I think is that, I mean I am not ...

Q:
You don't read Nuts or Zoo for example?

Tony Blair
: Look, compared with most of what I have to read, particularly about myself, it would probably be a welcome relief. (Ho.Ho. Ho.)

Then things started to get a bit more serious ..

Q. Why is the government moving towards a nuclear solution for Britain's energy production when there is ample evidence to suggest that the challenge of global warming and fossil fuel shortages can be better met through a decentralised energy production infrastructure embracing renewable fuels and energy sources?

Tony Blair
: " ....there is a simple stark fact that I would just like to put in front of people, which is we are going to go over the next 15 or 20 years to a situation where: one, the 20% that we get of our electricity from nuclear is going to decline to virtually zero; and two, where we are going to go from being 80 or 90% self-sufficient in oil and gas, to 80 or 90% importing it."

" ... whether we replace the existing nuclear power component of our electricity, but if we are not going to replace it we are going to have to, well what is going to happen on renewables is going to have to be absolutely massive."

"I don't know that we were voted in on a non-nuclear ticket, I think we have always kept the option open. But even if we weren't frankly, the fact is you have got an energy problem. "

"...I think I do not want a situation where people turn around in 15 - 20 years time and say what on earth were they thinking of, you know they ended up with a situation where we ran down our nuclear power stations, we thought we could get it through renewables and now we are wholly dependent on very, very expensive imports of gas and oil." really cannot gauge." (He actually means forecast or control).

" ...But to take out of that nuclear power and say that is it, well it is a very, very big step for us to take and I would need a lot of convincing that renewables were going to fill the gap.

To those who have been following the Energy needs of the country this represents the biggest shaft of light, a Damascene revelation that Tony Blair finally realises we have the Forthcoming UK Energy Deficit (FCUKED) to face.

Tony Blair finally tells the truth about the fucking shambles the UK policy (for want of a better word) is in ... has anybody noticed ?

What is vitally important to note is that Tony now belatedly understands ;

1.) If we run the nuclear "fleet" down the energy it produces has to be replaced.
2.) Despite what their lame brained last Energy Policy said he now realises .." I would need a lot of convincing that renewables were going to fill the gap." ... which is what all the rational critics said at the time and have repeated ad nauseam ever since.
3.) 15 years is now the time horizon we face these problems ..." where people turn around in 15 - 20 years time". The crunch is coming quicker than we imagined, thought, talked about.(probably 10 years see later)
4.) The cost implications of imported oil and gas is finally seeping through ..." now we are wholly dependent on very, very expensive imports of gas and oil." ...... he says elsewhere about how China is driving commodity prices up..."danger is that you end up not merely being dependent on imports, but dependent on imports whose price you really cannot gauge." (He actually means forecast or control).

What made the Dear Leader tell us like it is? Well my view is that the 6th report of the the Joint Energy Security of Supply Working Group (JESS) recently this May (the fifth of what should be bi-annula reports was published November 04.

For an excellent exegis of JESS 6 got to the excellent and superbly well informed Chris Vernon at Oil Drum. The reports factual information says basically what Our Dear leader told the magazine Editors last week.

To quote Chris ...."They expect continued increase in gas demand in the face of indigenous depletion with this demand being met by imports. The magnitude and timescales of reliance on imports is surprising though, previous reports have suggested 80-90% reliant by 2020. Forecasting 80% reliant by 2014-15 is the most pessimistic outlook I have seen." Hence Tony shortening his horizon from 20 to 15 years.

Perhaps most frightening (to the realist amongst us) Chris says..."Together this means by the end of 2015 the UK will lose 28.5% (8.2GW) of coal fired and 59.5% (7.1GW) of nuclear generation capacity." ... again forcing Tony to shorten his horizons.

In summary says Chris ..." this report has failed in its objective to provide the market with future supply, demand and price information. The quantitative data presented is so optimistic to be virtually worthless with qualitative caveats that don't adequately describe the risk." A view which will be widely shared by both energy producers and consumers.

Finally it takes a blogger (zceb90) to hit the spot which Tony has finally realised ...this 80% of fuel is imported and needs paying for.... zceb90 calculates it with gloomy accuracy .."Assuming UK gas demand for 2005 was around 1.7m Barrels of Oil equivalent per day (BOE/d), escalating at 2.2% pa through 2014 and assuming 80% imports the JESS forecast assumes that UK will be importing 1.65m BOE/d NG in 2014 (8 yrs away!) i.e. imports will amount to just slightly short of UK's 2005 entire consumption.

Using an import price of $100/BOE (which may well be extremely conservative by 2014 given increasing 'scramble' for scarce enery imports) gas imports would cost UK trade balance US$5bn per month or £2.8bn per month @ 1.80 exchange rate. Put another way projected gas imports by 2014 would more or less double existing trade deficit which is running at around £3bn per month.

As the Dear Leader told the magazine Editors .." now we are wholly dependent on very, very expensive imports of gas and oil.""

Tony Blair kept out of the Limelight (well almost).

On Friday Tony Blair went to Teeside to officially open the newly built plant (Teeside 1, Seal Sands) of Biofuels Corp plc. the largest in the UK, which is now (only 5 months after start up) at 58% capacity producing biodiesel from vegetable oils such as rapeseed, palm and soya beans.He must have met Mike Buzzacott BA. FCCA the Chairman and accountant who took over in March this year after 34 years at BP and was Group VP Petrochemicals.


(British Sugar started on Work in January on the UK's first bioethanol production facility from sugar beet with a new £20m plant to produce 70Mn litres of ethanol at Wissington, Downham Market in Norfolk.)The U.S. biodiesel market tripled in 2005.

The BBC report Mr Blair saying: "If we meet our Kyoto targets, we will only stabilise gas emissions.

"There's a big debate about whether energy should be renewable, nuclear or other but the reality is that we will have to go for every single possibility we can." (There he goes, telling the TRUTH again!)Interestingly, whilst the MSM misssed this visit the Northern Echo headlined the visit with this this quote and said "Blair sounds warning during visit to biodiesel plant"

When complete and running at peak flow the plant has a capacity to produce at least 250,000 tonnes of biodiesel each year (to EN14214 and EN590 standards) from vegetable oils, 25% of the 2010 Renewable Transport Fuel Obligation target for diesel.(2003 the UK prdocued about 5,000-6,000 tonnes per annum)

In November 2005 a target was set by the Gubment of a 20 fold increase in biodiesel production and that 5% of all motor fuel must come from renewable sources by 2010. Biodiesel costs 2.5 times to produce more than petrol, so an incentive fuel rebate is driving the market currently which Gordon Brown introduced in the last Budget.The rebate ( 25p per litre ?) of course only applies to the 5% of the biodiesel that is mixed with regular diesel.Plants such as this one also benefit from the 100% Enhanced Capital Allowance scheme for biofuels.

The company had previously announced construction delays and cost overuns at the facility and its stock has lost about 40 percent of its value during the last couple of months.

Biofuels Corp shares were trading at 1.24 pounds at 1245 GMT on Friday, up 7 pence or 6 percent but far below its peak of 3.22 pounds reached in March 2005. No Photo-op, no mention on the No 10 website, and the BBC got this quick and badly posed and taken shot with the back of Mr Buzzacotts head. How odd.

FOOTNOTE IN HISTORY

The last time TB opened an Energy co. office was for Cairn Energy PLC in Edinburgh. Cairn is run by Bill Gammell (Sir Bill since the New Year's Honours). Well in the tight knit world opening oilco offices, it so happens that Bill and Tony were at Fettes together and played fives.

The supreme coincidence is that Dad Genmmell (as very Blue chip Edinburgh Merchant Banker Sime Ivory) helped fund an outfit called Zapata oil run by ...George Bush Senior .. whose son George Bush Jnr (now POTUS) ... who used to come and play in the summer on the Gemmell family Renfrew estate (and Bill went to Kennebunkport), such good friends were they that George was Best Man at Bill's wedding... and when George was POTUS and came over to see his school chum Tony in November 2003, Bill was at Buckingham Palace browsing and sluicing with the best.History does not record any schoolboy George and Tony meetings... but it is possible.

As a further footnote, the browsers and sluicers at Her Maj's invitation was another Yank. Mrs Quinn. Helpfully the then Home Secretary, David Blunkett, dog handler and father of the child William, then stirring within her loins, was able to accompany her - not that the Press noticed at the time.,, or of they did forgot to tell anyone.

Another footnote is that when Gemmell pere slid George Senior out of (loss making) Zapata Petroleum it changed a bit and ended up as the major company in Mr Glazier's stable of companies (including Man U) but selling fish oil.

I don't think Mr Buzzacot was at Fettes, but it's a small world.

Tuesday, October 17, 2006

UK Energy Security - Nuclear Con - Fusion (2)

In 2005 UK based electricity generation totalled 398 terawatt-hours,of which 61-63 terawatt-hours is generated by British Energy PLC who operate 8 nuclear power stations with a total capacity of 9,568 megawatts.he company also operate a coal fired plant at Eggborough with a capacity of 2,000 megawatts.

Due to a "leak" underground at the Hartlepool plant the reactors were shut down last month and their re-opening has been delayed. The work required might indicate similiar work needs also to be undertaken at Heysham 1.

Today the company announced that 2 more reactors have developed problems resulting in the need to close down the reactors...."a level of boiler tube cracking at the high end of the range previously experienced."

Hinkley point B has an installed capacity of 1,220 megawatts, while Hunterston B's is 1,190 megawatts, both are gas cooled reactors, and came on stream in February 1976, their design life ends in 2011.

The company also report problems with fuelling at Dungeness B which will result in unplanned outages - and one unit at Heysham is operating at reduced load due to "temperature anomolies".

It is early to calculate the effect on production of these problems but informed estimates consider that these closures will reduce annual output by at least 10% and as much as 15% cutting total national production 3/4% - when dmeand is growing at 1-2% annually. The repairs will of course add massively to operating costs.

There will be other effects...

UK Domestic electricity prices will rise both short and long term - increasing industrial costs and impacting on houehold costs to drive up inflation.

Production from other coal / gas fired plants will drive up CO2 emissions - making EU emission targets more difficult / impossible to acheive.

British Energy share price dropped dramatically today - 25% which will reinforce the nervousness of investors about the massive costs of replacing the current nuclear plants - making decisions about the financing, building and commissioning nuclear plants even more problematic for a Gubment with a new found, but unpopular belief in new UK nuclear plants.

However someone WAS planning and Dusseldorf based E.ON, Europe’s second-biggest utility after France’s state owned EDF, operates in the UK as Powergen, who announced in December they were planning a new "clean" coal fired station and announced last week plans to build two new 800-megawatt so-called "supercritical" units at Kingsnorth, in Kent. Supercritical means, slightly more efficient, slightly less emissions and much, much higher operating costs and increased future coal imports. Overall these will replace the present units at the site so do not add significantly to UK total electricity production.

E.ON UK has already applied for S36 consent to build two new gas-fired power stations, at Drakelow in Derbyshire and at the Isle of Grain in Kent, and is conducting a feasibility study into building a clean coal power station at Killingholme in Lincolnshire.

It would be unwise to suggest that this Gubment after 9 years in office has an "Energy Plan" but what plans they had for electricity generation are looking increasingly flaky, costly, reliant on overseas shareholders and suppliers of fuel and result in more CO2 emissions.

UPDATE
An interesting piece at Money Week which re-inforces above views.

Sunday, May 20, 2007

IEA getting serious about energy security - well they are talking about it

The International Energy Agency (IEA) was set up by industrial countries in 1974 to counter OPECs boycotting power. Amongst many obligations the 24 members, but as they describe it , " Emergency response to oil supply disruptions has remained a core mission of the IEA since its founding in 1974." - members must maintain emergency oil reserves equivalent to 90 days of net imports.

The European Commission’s proposed in 2002 to increase stocking obligations from 90 days to 120 days, but Member States and the Parliament opposed. This proposal was effectively withdrawn in 2003 and no proposals have been made since.

In a little noticed proposal on 15 February 2007 the European Parliament in its resolution on the macro-economic impact of the increase in the price of energy recommended both an increase to 120 days and more frequent stock reporting.

In a briefing paper Her Majesty's Government that arrived on Lord Patel's desk in a buff envelope) have identified some areas raised by the Commission, which in principle they support:

1. Reducing differences between the EU and IEA stocking systems; (to stop any fiddling in reporting)

2. Reviewing the categories covered to reflect market changes; (since 1974)

3. Replacing the requirement for treaties between member states as a condition for cross-border holdings with a more rigorous reporting system. (to stop any bi-partisan fiddling)

Overall it is encouraging that HMG and the European Parliament are taking some steps to ensure energy security. However legislative proposals will not see light of day until 2008 and then it will be some time after when anything is actually done to increase European oil reserves by 1/3rd.

The IEA produce a useful downloadable pdf "Fact Sheet on IEA Oil Stocks and Response Potential-" it is significant that this was updated on May 7th 2007.

This pamphlet explains the decisionmaking process for IEA collective action, the measures available – focusing on stockdraw – with a history of major oil supply disruptions and the IEA response to them.It also demonstrates the continuing need for emergency preparedness, including the growing importance of engaging key transition and emerging economies in dialogue about energy security.

On the 14/15th May the Ministers from the 26 IEA member countries plus accession countries Poland and the Slovak Republic, met for their bi-ennial meeting in Paris - the public were excluded. Topics were ;

- Dealing with the Short-Term Risks to Energy Security;
- Improving Longer Term Energy Security;
- The Crucial Role for Energy Efficiency;
- Technologies for a Sustainable Energy Future.

The full communique issued to the Press is available here some points worth noting in all the PR bullshit -

We welcome and consider implementing as soon as possible, further recommendations such as energy efficiency standards for new buildings, fuel efficiency standards for vehicles, and mandatory appliance standards.

We will enhance our programmes for the deployment of renewables and, subject to national policies, nuclear power, to cope with the emerging threat of global warming.

We will promote clean coal
(Oh yeah ?) and press ahead through the IEA and the Carbon Sequestration Leadership Forum (CSLF) with the full scale demonstration and early deployment of Carbon Capture and Storage, paying due regard to regulatory and safety issues. (14 May 2007 Reuters reports that the IEA's coal analyst Brian Ricketts (see picture at top) introduced a note of reality when he said that "coal in power generation use could grow by 1% per annum in the next 25 years in Europe's OECD countries", and went on to say that if environmental controls are stringent, there will be no initial growth, and a decline will occur. - Note - Germany plans 15 new coal plants by 2012 because it is cheaper to burn coal than more environmentally friendly gas apparently they maintain that coal only beomes unattractive if the ETU of CO2 emission allowances rose to Euros 45 euros (US$60.64) would gas be favourable for power generation - The Uk and Netherlands plan more coal fired power stations)

We need to respond to the twin energy-related challenges we confront: ensuring secure, affordable energy for more of the world’s population, and managing in a sustainable manner the environmental consequences of producing, transforming and using that energy.

The world can achieve a clean, clever and competitive energy future.

It is possible they also voted for motherhood and apple pie as well.

(C) Very Seriously Disorganised Criminals 2002/3/4/5/6/7/8/9 - copy anything you wish